When the ATO pre-fill doesn't match the client
The pre-filling report says one figure and the client's statement says another. How to find the cause, record it, and stop the file quietly choosing a side.
The pre-filling report has a line of interest income from an account you have never heard of. Not a big amount. Big enough to matter, small enough that the client, asked on the phone, says "that's not mine" with total confidence and then goes back to whatever they were doing.
So you have two numbers. One from the ATO, which came from a bank. One from the client, which came from the bank statements they remembered to send you. And a return that can only carry one of them.
What happens next is usually invisible. The preparer picks one, types it in, and moves on. Maybe they picked correctly. The file will never say which they picked or why, and that is the problem this post is about.
The pre-fill is a second source, not the answer
The ATO frames pre-fill exactly that way. Its About pre-filling page describes the service as a way to cross-check what your client gave you against what organisations reported, and says plainly not to rely solely on it. The data can be late because a provider has not reported yet, missing because it could not be matched to your client, or held back because it failed processing checks.
Which means a mismatch can come from either direction. The pre-fill can be short because the data hasn't arrived. It can be long because it caught an account the client forgot. It can be wrong because the provider reported it wrong. And the client's figure can be wrong for every reason a client's figure is ever wrong.
Copying the pre-fill over the client's records is choosing a side. So is ignoring it. Neither is a reconciliation.
Find the cause before you pick a number
Timing. Is the pre-fill complete yet? Employment income statements carry a status, and the ATO's Pre-filling 2025 contents page says to wait until an income statement is finalised before completing the return. A pre-fill pulled early and saved into the file is a snapshot of a moving thing. Note the date you pulled it.
An account the client didn't know about. The ATO's Missing information and discrepancies page lists the usual sources of unrecognised interest: securities reported by a share registry rather than a bank, accounts the investor has overlooked, and accounts opened on the client's behalf that they don't know exist. "That's not mine" is a starting point, not a finding.
Joint ownership. Joint accounts and investments are apportioned by the number of owners the institution reported. If the client holds something in unequal shares, or the institution has the owner list wrong, the pre-fill and the client's records will disagree for a reason that has nothing to do with the income.
The provider got it wrong. It happens, and the ATO says so. The same page says the provider must correct the information with the ATO if there has been an error. For managed fund and partnership distributions, the 2025 contents page goes further: if the pre-fill doesn't match the statement the fund or partnership gave your client, use the statement your client received.
The client's records are incomplete. The other half of the list, and the more common one in practice. A statement for eleven months out of twelve. A second bank account the client didn't think counted because "it's just the savings one".
Only once you know which of these it is do you know which number belongs on the return.
Resolving it is the client's job; recording it is yours
The ATO's position on discrepancies is consistent across its agent pages: check the client's records to find the cause, then have the client clarify it with the information provider. The 2025 contents page says discrepancies between what a provider sent the client and what it reported for pre-fill need to be resolved with that provider before you lodge. Where that fails, or an account plainly doesn't belong to your client, the ATO asks agents to contact it through Online services for agents, under a message subject for incorrect pre-filled data.
None of that is the interesting part for a practice. The interesting part is what the file looks like afterwards.
What the working paper should show
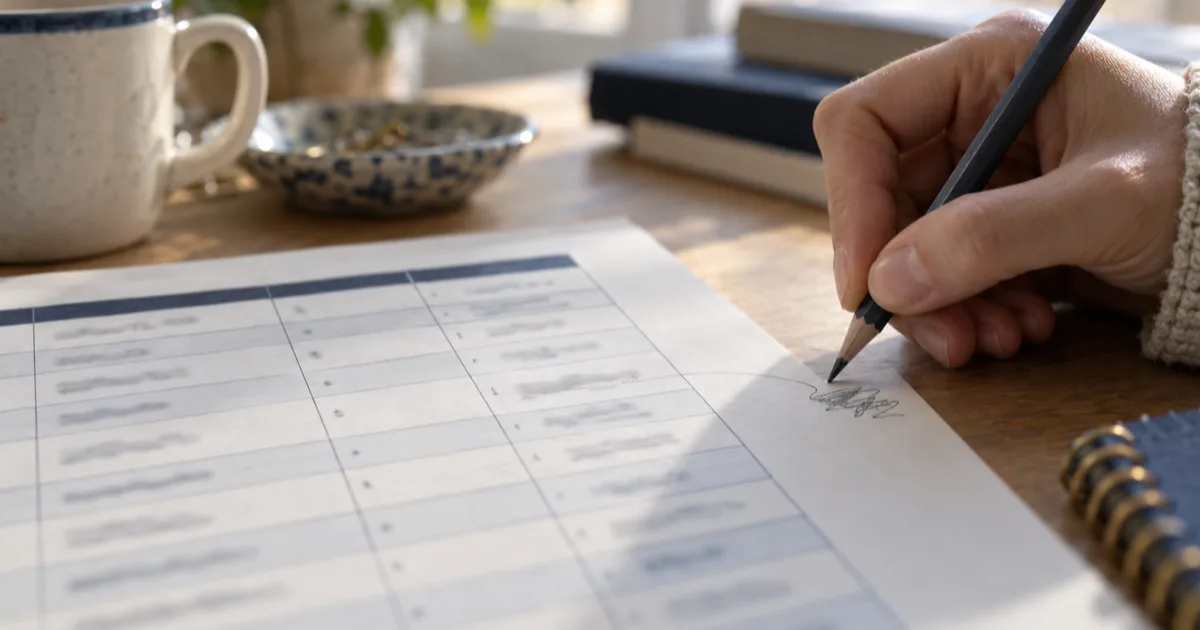
In practice that means three columns where most schedules have one: what the pre-fill says, what the client's documents say, and what went on the return. Where all three agree, it is a tick. Where they don't, the row carries a short note:
- the cause you found, in a sentence
- the document that settles it, referenced to the page
- what you asked the client or provider to do, and when
That isn't paperwork for its own sake. The missing information page is direct about why it matters: pre-filling does not change your responsibility to lodge a complete and correct return, and if a lodged return is audited, the ATO may consider whether the taxpayer or agent had accessed pre-filling information they chose to leave out when it applies penalties or interest. A note written at the time is the difference between "we looked at it and here is why" and a departure nobody can explain.
It also makes next year cheaper. The same unrecognised account tends to come back. If last year's file says what it was and who confirmed it, this year it takes a minute.
This is the same principle as why workpapers come back from review: the reviewer is following a figure back to its source. A pre-fill difference with no note is a figure with two sources and no explanation of why one was preferred.
When you can't resolve it before lodging
Put the open difference in front of the reviewer as a question, with what you know so far. Don't settle it quietly inside the schedule because the file "needs to be finished". A preparer who picks the client's figure to get the file out the door has made a decision for the practice without telling anyone, and that decision has a name on it at lodgment.
If the return is lodged with a difference still open, the file should say so, and somebody should own the follow-up. An amendment you planned for is a much shorter conversation than one you discovered.
Where BeforeMay fits
When a client's pre-filling report is uploaded with the rest of the file, BeforeMay reads it alongside the client's own documents. Each figure in the working paper keeps a reference to the document and page it came from, and anything the build can't settle comes back as a review point with its reasoning shown, instead of being resolved quietly inside a subtotal. The judgement stays with you. Our tax working paper templates show the layout, and the FAQ covers how client documents are handled.